Floating Home Escrow In California
Floating home escrow is a specialized closing process that handles ownership transfer for homes on the water. It is not a standard residential closing, and the details matter from the first offer to the last signature. If you are buying in Sausalito or Marin, floating home escrow shapes the whole transaction, from title work to marina approval to tax clearance.
Floating Home Escrow
Floating home escrow starts with a signed purchase agreement and an opened file, then moves through document review, marina coordination, HCD title transfer, and county tax clearance. Because a floating home is titled through California’s HCD system, the transfer follows a personal property process rather than a county deed recording. That one detail changes the entire path of the deal.
The berth lease is another major piece. The home may be sold, but the slip belongs to the marina, so the buyer has to be approved as the new tenant. That approval can include a marina application, financial review, and a look at current fees or lease status. If the marina is slow, escrow slows with it.
Floating home escrow also has to account for insurance, any lender requirements, and any unpaid liens tied to the home. If financing is involved, the lender may need a security agreement instead of a deed of trust. That means more documents, more review, and a longer runway before closing.
The process can feel like a juggling act, but each piece has its place. Buyers who understand the moving parts tend to have fewer surprises and fewer late-night “wait, what now?” moments.
What Makes The Process Different
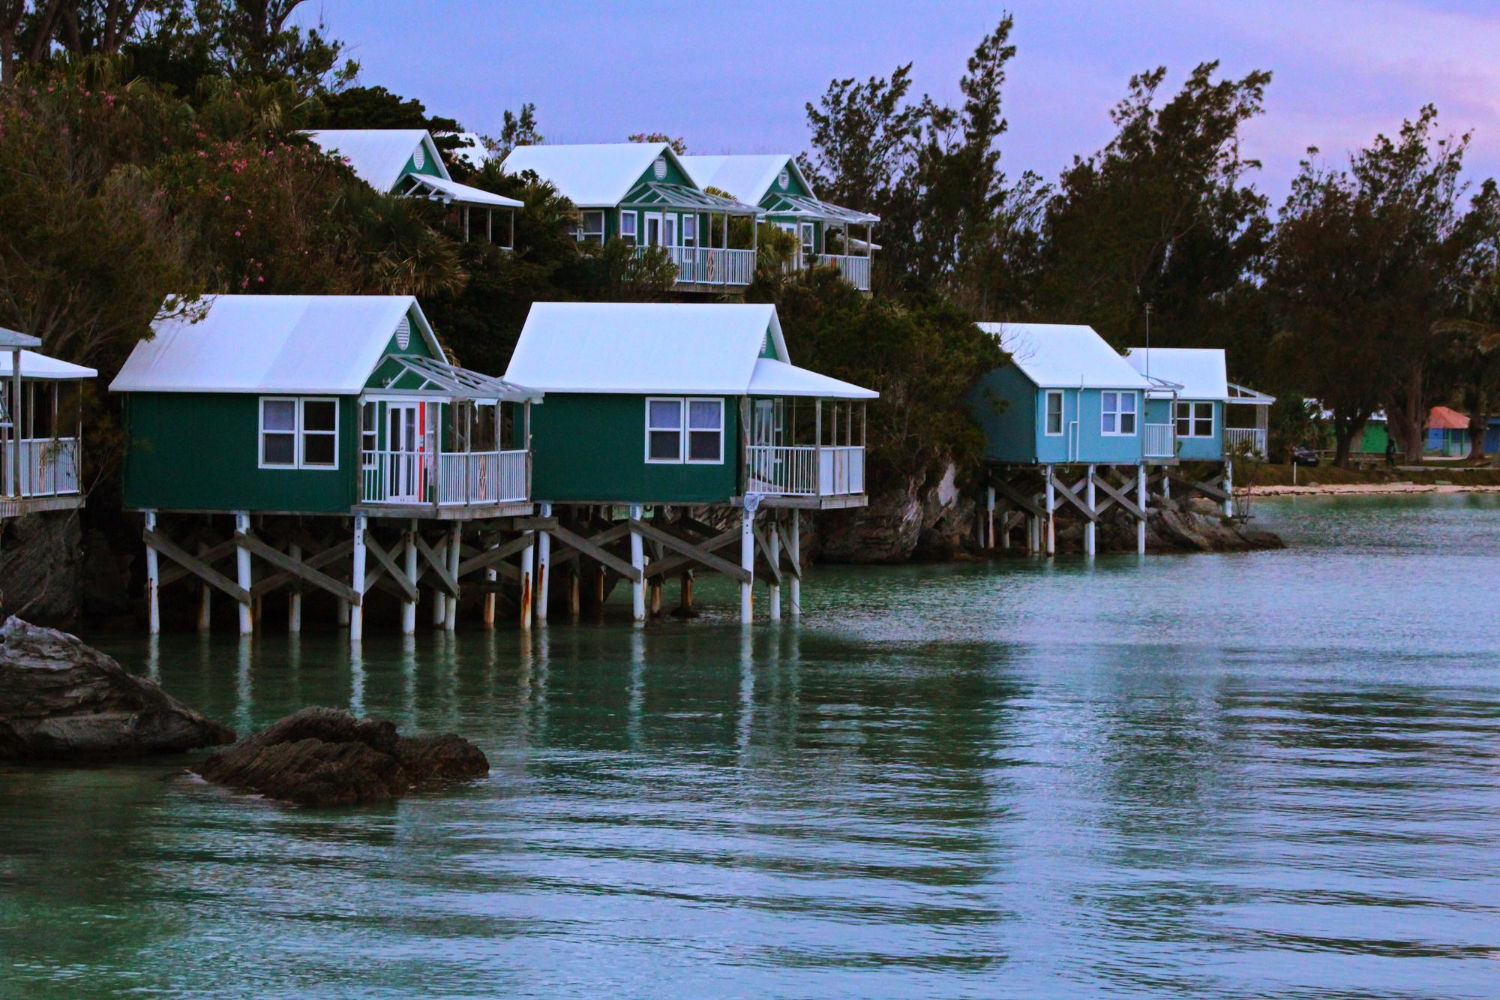
A floating home is not a land-based house with a fancy view. It is a waterborne structure that sits in a marina slip and carries its own set of title, lease, and tax rules. That means the buyer is not simply purchasing a home, they are stepping into a system that includes state titling, marina consent, and tax checks.
The HCD title transfer is one of the biggest differences. Instead of a county deed, the ownership change happens through state paperwork that must be completed correctly. If the title packet is missing details, the file can stall fast.
The marina side also changes the flow. The buyer may need to submit an application, provide income or background information, and wait for approval before the berth lease can be assigned. In Sausalito, where floating homes are a distinct and tightly managed market, marina rules can carry a lot of weight.
A floating home may also require a different insurance setup than a typical house. Lenders often want proof of coverage before funding, and some carriers write floating home policies with special conditions. That is one more reason floating home escrow needs early planning instead of last-minute guessing.
What Buyers Need To Prepare
Buyers should start by asking for the HCD title status, the marina lease terms, the current moorage fee, and the county tax record. Those four items tell a lot about how the close will go. If any one of them is messy, the file deserves attention before contingencies are removed.
It also helps to know whether the seller has kept up with maintenance. Buyers in floating home markets often focus on the beauty of the setting first, then learn later that the float, exterior, or utility hookups need attention. A careful review of the home’s condition can save real money after closing.
Insurance should move early too. A lender may not fund the loan until coverage is in place, and buyers do not want to be hunting for a policy three days before the close. Getting quotes early helps avoid that scramble.
The same goes for any lender paperwork. Floating home financing can take longer than standard residential lending because the structure is titled differently. If the buyer’s lender has never handled a floating home before, the learning curve can slow things down.
How Marina Approval Fits In
The marina is one of the quiet gatekeepers in the process. The home may be under contract, but the buyer still has to satisfy the marina’s requirements to take over the berth. Some marinas want a formal application. Others want income proof, references, or an interview.
That approval is not just a box to check. It is the difference between owning a floating home and having nowhere to keep it. A buyer who waits too long to start the marina process can find themselves boxed in by a closing date that no longer matches reality.
A strong escrow file builds marina timing into the schedule from the start. The seller should be ready to request the assignment package quickly, and the buyer should be ready to return the paperwork without dragging their feet. The faster that part moves, the less likely the closing is to wobble.
If you want a closer look at the marina side of the transaction, the floating homes page gives helpful background on how these properties differ from land-based homes. The key thing to remember is that the marina is not a side detail. It is part of the deal.
Why Tax Clearance Matters
Floating home escrow usually includes a county tax clearance before the HCD transfer can close. That clearance confirms the county record is current and there are no unpaid taxes that need attention before title can change hands. If the tax record is not clean, the file may need to pause until the issue is fixed.
This step matters because buyers do not want to inherit a problem that should have been caught earlier. A current tax record helps the transfer move through smoothly, while an unpaid balance can trigger delays and extra follow-up. In a deal with several moving parts, that kind of delay can affect everything else downstream.
Marin County may process records differently from other counties, and floating home buyers should not assume the clearance will come back instantly. An experienced escrow officer watches the timeline closely and follows up as needed so the request does not sit untouched.
What Escrow Actually Does
Escrow is the coordination point that keeps the transaction moving. We do not approve the marina application, set the tax rules, or issue the HCD title. What we do is track each step, collect the right paperwork, and make sure the file moves in the proper order.
That means preparing instructions, confirming the deposit, following up on the marina approval, requesting tax clearance, and coordinating with the lender if financing is involved. It also means watching for missing signatures or documents that could hold up the file. In floating home escrow, small mistakes can ripple quickly.
We also help make sure the closing statement reflects the correct prorations and fees. That includes moorage, taxes, and any other items the parties agreed to handle through escrow. When everything is assembled cleanly, the close feels less like a scramble and more like a finish line.
The process can overlap with other transaction types too. If the property involves a manufactured home escrow style title issue, or if the transaction needs holding escrow for a timing gap, those elements need attention early as well. Floating home files reward careful planning.
What Can Delay Closing
A delayed marina approval is one common holdup. Missing tax clearance is another. If the lender is unfamiliar with floating home files, underwriting can take longer than expected. A title packet with errors can also bounce back and slow the whole process.
Sometimes the delay comes from simple paperwork friction. A buyer misses a signature, the seller forgets to return a form, or the marina asks for one more document after reviewing the application. None of those issues is rare, but each one can eat up time fast.
That is why floating home escrow works best with a clear, early timeline. Buyers who wait until the final week to ask questions often end up paying for it in stress, and nobody needs that kind of extra seasoning in the closing stew.
What A Buyer Should Ask Before Removing Contingencies
Before removing contingencies, a buyer should confirm that the HCD title is in good shape, the marina lease can be assigned, and the tax clearance request is underway. They should also check that the insurance quote is realistic and that the lender understands the title structure. Those questions are practical, not fussy, and they save headaches later.
Buyers should also ask who is responsible for each step. If the seller is still waiting on a marina form, the buyer should know that. If escrow is waiting on the county, the buyer should know that too. A clean transaction is usually the one where nobody is guessing.
FAQs
How is floating home escrow different from a normal home closing?
Floating home escrow uses HCD title transfer rather than a county deed recording. It also requires marina approval and tax clearance before the file can close.
Why does the marina need to approve the buyer?
The marina controls the slip, so the buyer must be accepted as the new tenant. Without that approval, the home may not have a legal place to stay.
What is HCD title transfer?
It is the state process that changes ownership of the floating home. The title is handled through California’s HCD system, not through a standard real estate deed.
Do floating home buyers need a special insurance policy?
Yes, in many cases. Lenders often require a policy written for the marine environment, and coverage terms can differ from a regular homeowner’s policy.
Why does tax clearance matter so much?
The county has to confirm the record is current before title can move forward. Unpaid taxes or stale records can hold up the closing.
Can escrow help if the closing date gets tight?
Yes. Escrow can track the moving parts, follow up with the right parties, and help the file stay organized while the approval and clearance steps finish.
Ready To Open Escrow?
If you are buying or selling a floating home and want the closing handled with care, contact our team at Bay Area Escrow. Call (925) 831-9099 and we will help you move the file forward the right way.